The essentials
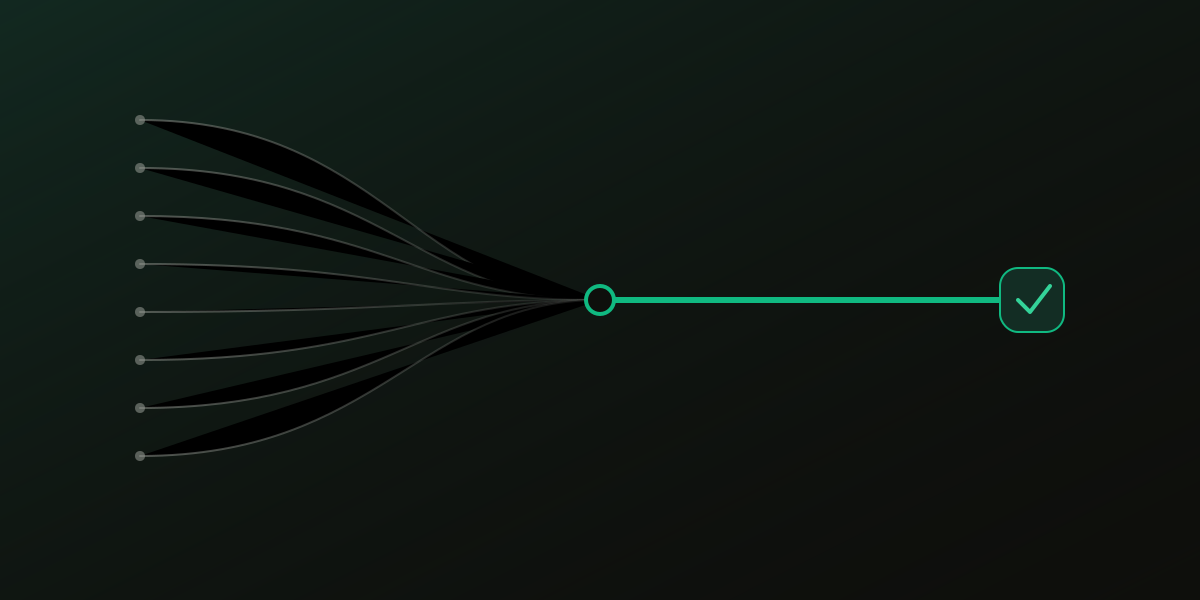
- An SPV is a company incorporated for one thing only: to group investors together and to enter the share capital of another company with them, as a single shareholder.
- Your cap table goes from hundreds of lines to one. The relationships do not disappear: they happen inside the vehicle.
- The investor keeps their economic rights; what changes is the route through which they exercise the voting ones.
- It has to exist before the first euro is raised. Rebuilding it afterwards is expensive and sometimes unfeasible.
What it actually does
SPV stands for special purpose vehicle. It is a company incorporated for one thing only: to group a set of investors together and to enter the share capital of another company with them, as a single shareholder.
Without a vehicle, each investor enters your company directly and takes up their own line on the cap table. Four hundred investors, four hundred lines, four hundred signatures every time something has to be signed.
With a vehicle, the four hundred enter that intermediate company, and it is the intermediate company that appears on your cap table. One line. The four hundred relationships still exist, but they happen inside the vehicle, not inside your company.
Why the number of lines matters so much
Because a cap table is not an accounting document: it is a map of how many people have to be convinced in order to take a decision.
- The next round. A fund looking at your Series A opens your cap table before your income statement. A cap table with hundreds of minority holders reads as execution risk, not as proof of traction.
- Shareholders' meetings. Every resolution that requires a general meeting requires convening all of them, with the corresponding notice periods and formalities.
- A sale. The buyer will want one hundred per cent, or something very close to it. Gathering that agreement among hundreds of scattered people is slow, and slow in an acquisition is expensive.
The vehicle does not remove those investors. It concentrates their representation, which is a different thing.
What the investor loses and what they keep
They keep the economics: their proportional share in the value of the vehicle and, through it, in the value of your company. If the company appreciates, their position appreciates.
What changes is the route through which they exercise their voting rights. They do not vote directly at your company's general meeting: they take part in the vehicle's decisions, and the vehicle votes as a single shareholder. That has to be explained clearly in the issuance document and in the shareholders' agreement, because it is exactly the point a retail investor is entitled to understand before putting money in.
When it makes sense and when it doesn't
It makes sense when you expect many investors with small tickets, which is exactly the profile of a round aimed at your own customer base. It also makes sense when you want to be able to repeat the exercise: the vehicle becomes the stable route through which your community comes in, round after round.
It does not make sense if you are going to raise from three or four professional investors. There the vehicle adds a corporate layer, with its costs and its obligations, to solve a problem you don't have.
| Scenario | With a vehicle | Without a vehicle |
|---|---|---|
| 400 investors of €1,000 | Recommended | Unmanageable cap table |
| 4 professional investors | Cost with no benefit | Direct entry |
| Repeated community rounds | Recommended, it is reused | Worse with every round |
| Future sale of the company | One counterparty | Hundreds of counterparties |
Three common mistakes
- Setting it up late. The vehicle has to exist before the first euro is raised. Rebuilding it afterwards, with the money already received, is expensive and sometimes unfeasible.
- Treating it as a formality. It is a company: it has accounts, obligations and someone answering for them. If nobody runs it, it degrades.
- Forgetting the register. Knowing who holds what, at all times and in a way that can be evidenced, is not an administrative detail: it is what turns a promise into ownership. In a regulated issuance that function is covered by the entity responsible for administering the registration and the register (Art. 8 of Law 6/2023), which carries out the registration of each holding (Art. 10) and issues the legitimation certificates (Art. 14).
Frequently asked questions
Is an SPV investor a shareholder of my company?
Indirectly, yes. They are a member of the vehicle, and the vehicle is a shareholder of your company. Their economic interest in the value of the company is proportional and real; what they exercise through the vehicle are the voting rights.
How much does it cost to maintain a vehicle?
It is a company, so it has the recurring costs of any company: bookkeeping, annual accounts, tax obligations and the administration of the relationship with its members. It is a modest fixed cost compared with managing hundreds of direct shareholders, but it has to be budgeted from the start and someone has to be put in charge of running it.
Can I set the vehicle up after the round, once I have the investors?
In practice, not cleanly. Moving hundreds of already registered shareholders into a later vehicle requires gathering each of their individual consents and redoing corporate transactions that are already closed. It is the most expensive of the three mistakes, and the easiest to avoid.
Can the same vehicle be used for several rounds?
Yes, and that is one of its advantages. Well designed, the vehicle is the stable route through which your community comes in: the second round increases capital inside the same vehicle instead of opening a new structure.
Legislation and sources cited
- Law 6/2023 of 17 March on Securities Markets and Investment Services (BOE-A-2023-7053). Arts. 8 (entity responsible for the register), 10 (creation of the securities) and 14 (legitimation certificates).
Updated 16 Sep 2026. This article is for general information and does not constitute legal or financial advice. The specific terms of each transaction depend on its structure and should be reviewed with professional advice.